This content is not available in your region
VC63-This Is Why The Rate Drop Won t Save Your Mortgage. Here s What Will. - Velocity Channel
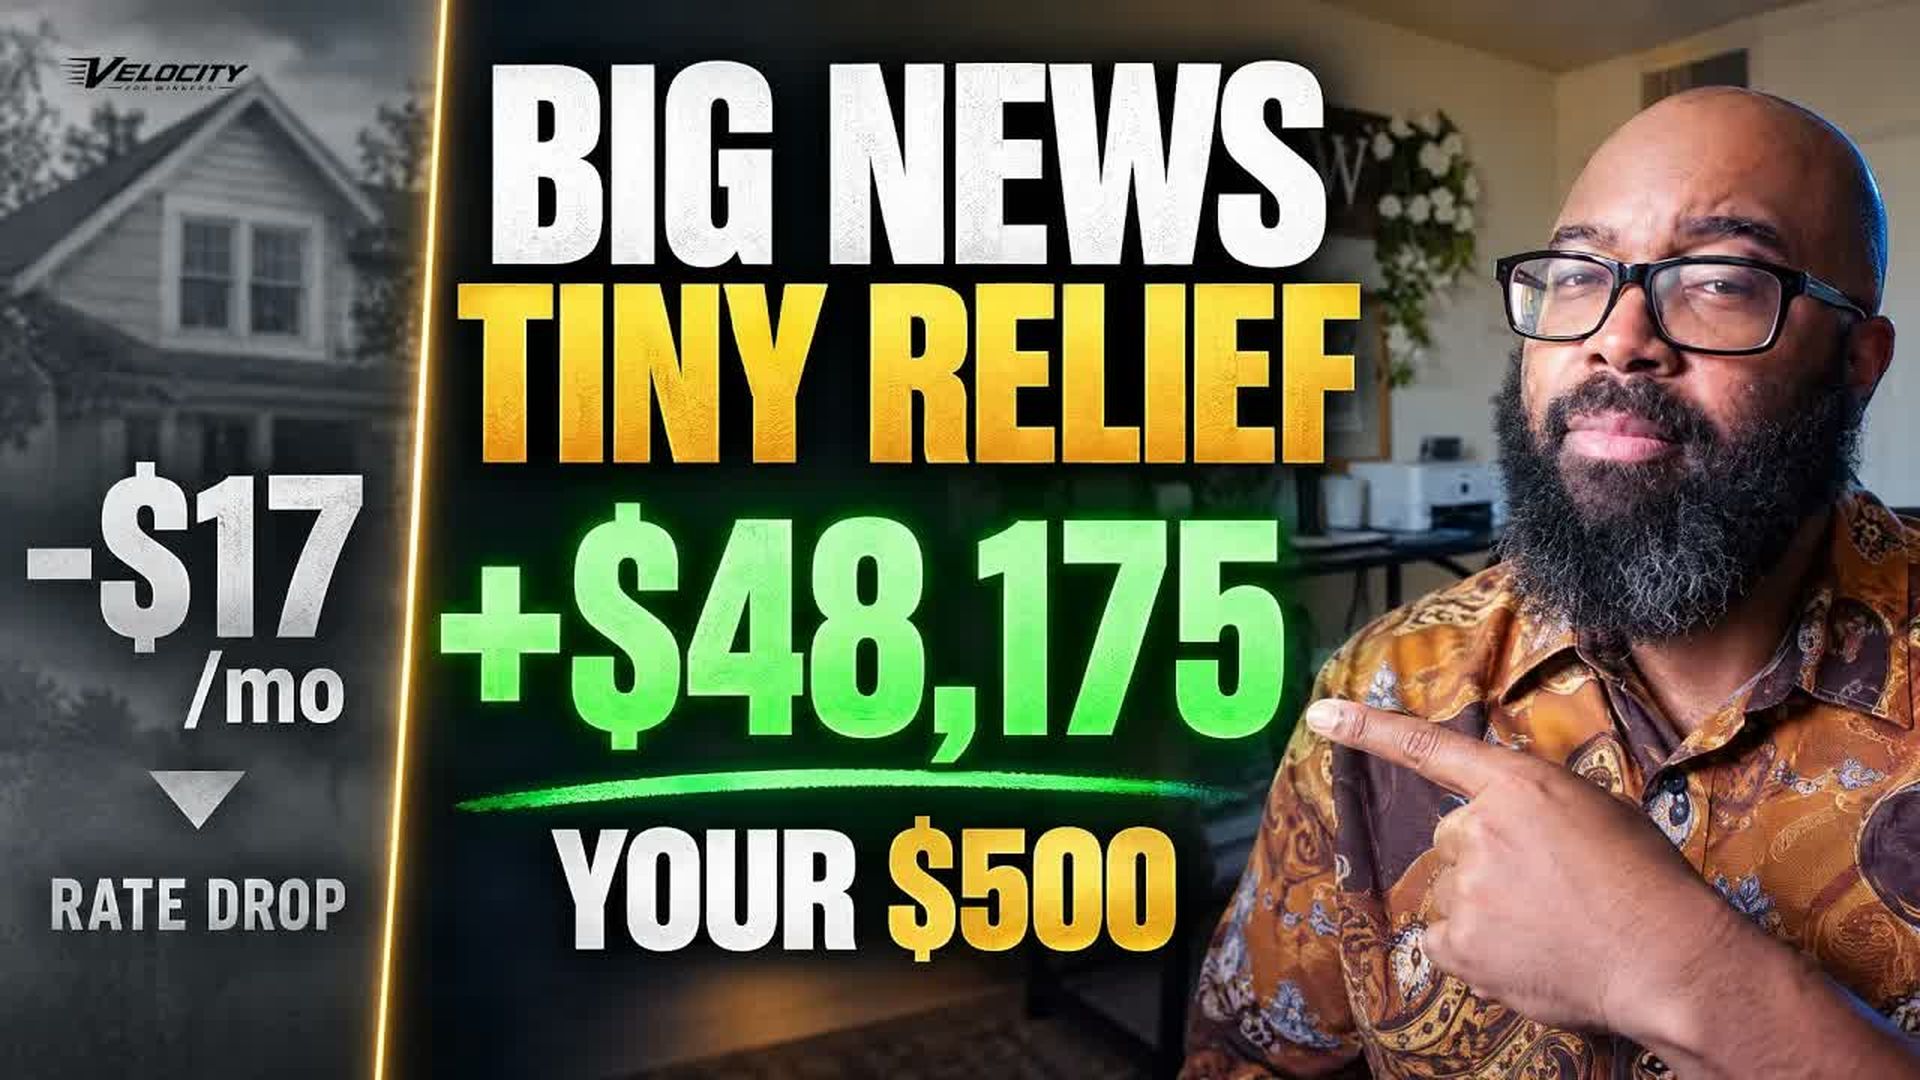
CJ Wallace breaks down why the hype around falling mortgage rates is a distraction and shows how a disciplined extra‑payment strategy beats waiting for the market to move. He starts with a stark comparison: a 30‑year fixed at 6.19% costs $86,527 more in interest than the same loan a year earlier at 5.99%, yet the headline news only highlights a $17 monthly relief. Wallace then demonstrates the power of adding $500 to principal each month on a $320,000 loan. At today’s 7.32% rate the loan shrinks from 360 months to 217 months, slashing 143 months and saving $172,886 in interest. He walks through the mechanics—interest is calculated on the outstanding balance before any principal reduction—so higher rates actually make each extra dollar work harder.The host expands the analysis across a range of rates, proving that the higher the rate, the larger the term reduction from a $500 extra payment. Whether rates sit at 3% or 11%, the extra‑payment strategy always outperforms waiting for a rate drop. Wallace stresses that borrowers cannot control the Federal Reserve or bond market, so the only controllable lever is disciplined principal reduction.Next, he compares a 30‑year loan with extra payments to refinancing into a 15‑year at a slightly lower rate. The refinance yields a higher mandatory payment ($2,819 vs. current $2,198) but guarantees the faster payoff. In contrast, the $500 extra payment remains optional, allowing flexibility for life’s curveballs. The decision, Wallace says, hinges on personal cash‑flow stability and willingness to lock in a higher payment.Finally, Wallace gives a concise action plan: pull the principal‑and‑interest portion of your mortgage statement, calculate your true surplus from 90 days of statements, and apply that surplus as an extra payment this month. By turning a simple arithmetic insight into a habit, homeowners can keep $325,000 out of their pockets over the life of the loan and retire years earlier.This episode equips listeners with the bold, counter‑intuitive math that turns a high‑rate environment from a curse into a catalyst for financial freedom.
Categories: Money