This content is not available in your region
VC62-vs 500 A Month On Your Mortgage - The Real Math They Never Show You 12 Years - Velocity Channel
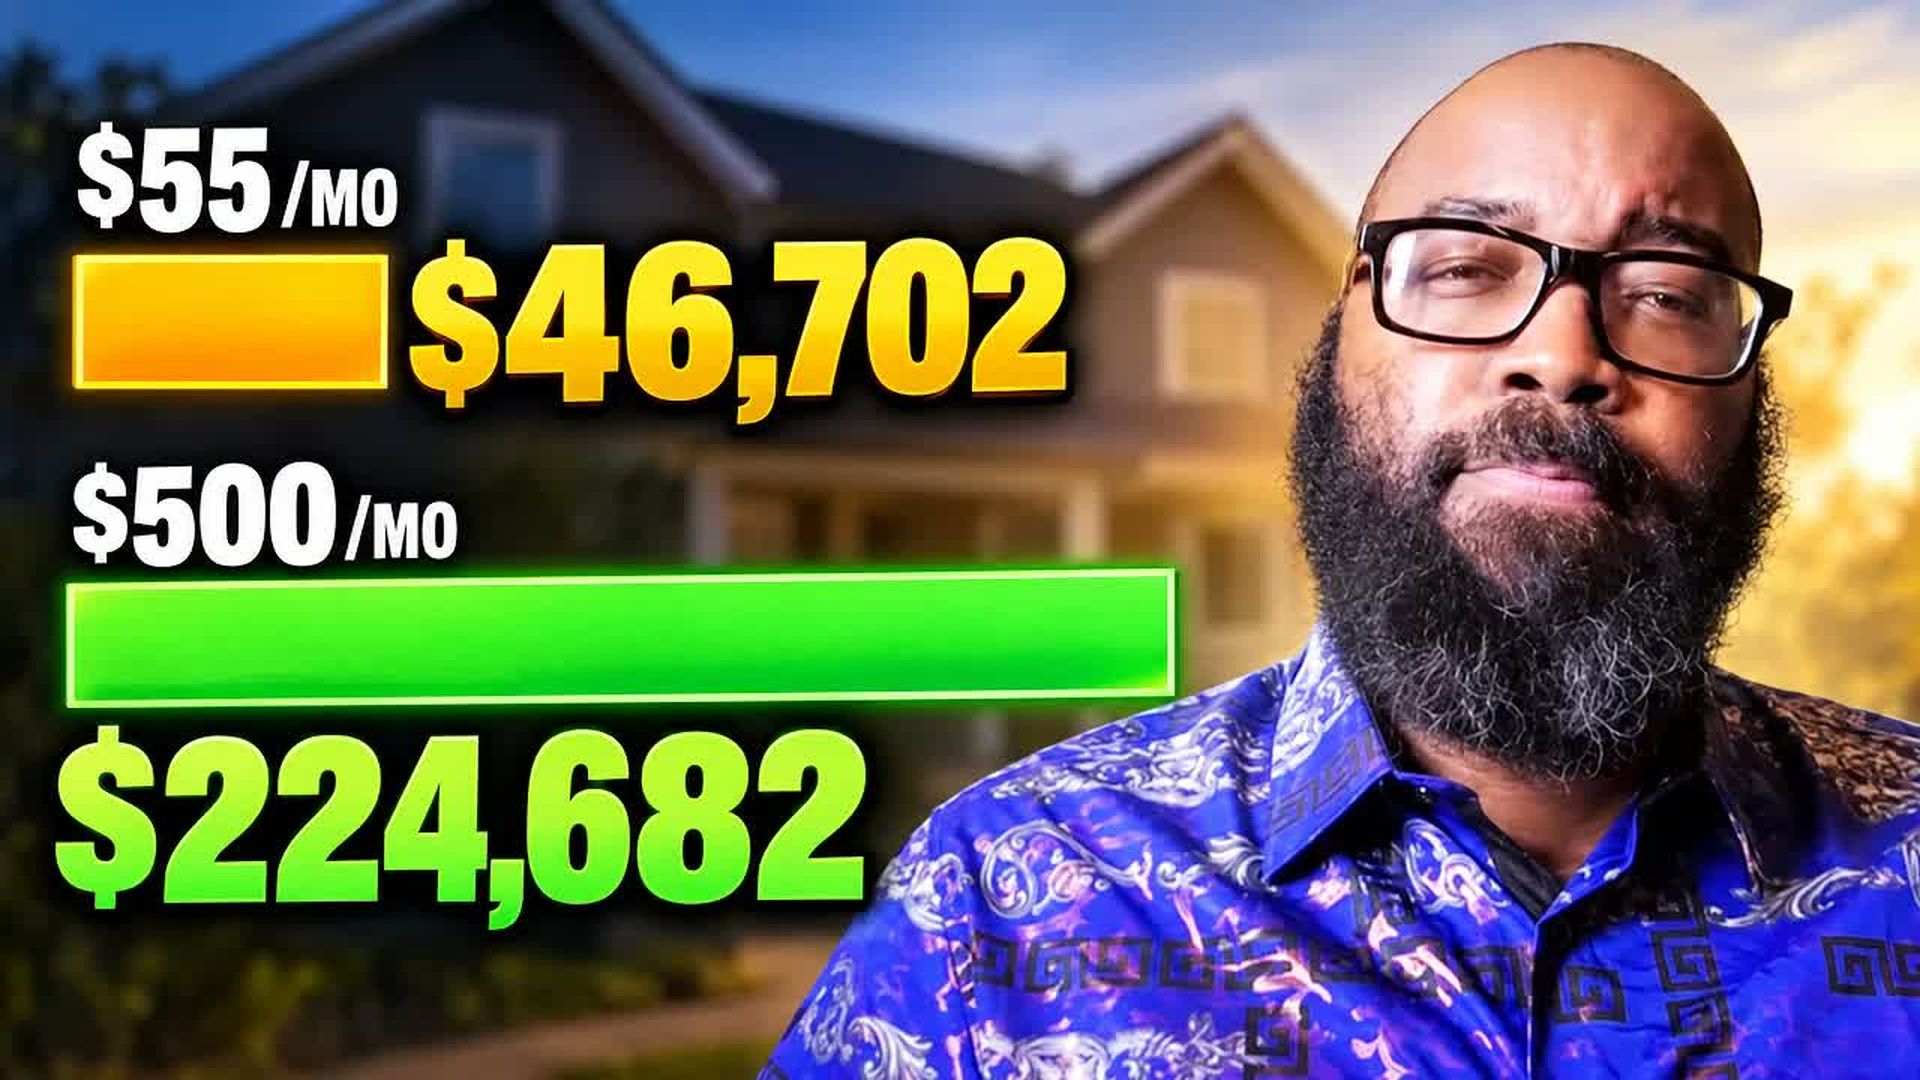
In this deep‑dive, CJ Wallace breaks down the math behind tossing either $55 or $500 extra each month toward a 30‑year, $320,000 mortgage at today’s 7.40% rate. He starts with the raw numbers: a $55 extra payment trims the loan to 331 months, shaving off 29 months and delivering $46,702 in avoided interest. A $500 extra payment slashes the term to 211 months, cutting 149 months and saving $224,682. The headline‑grabbing fact? Nine times the money ($500) yields only about five times the benefit in months saved, and the per‑dollar return drops from $2.57 for the $55 plan to $2.13 for the $500 plan. Wallace emphasizes that early dollars are the most powerful. A $55 payment in month 1 eliminates roughly $500 of future interest, while the same $55 in month 240 only saves about $115. This timing effect fuels his “escalator” strategy: start with $55, then add another $55 each year, building a realistic, sustainable payment path that captures the high‑impact early dollars without the drama of a $500 launch. He also tackles rate‑environment myths. Whether the mortgage sits at 5% or 11%, extra principal attacks always shave months off the schedule—more so as rates climb. The takeaway isn’t “small payments are useless”; it’s that they are the most efficient use of cash, while larger payments deliver dramatically larger absolute savings when you can afford them. The episode then pivots to Velocity Banking, the tool CJ uses to funnel surplus cash through a line of credit. He warns that the line’s interest must sit below the mortgage rate for any net gain; otherwise the method merely adds a 2.3% cost overlay. The core lesson: the surplus itself is the hero, not the banking trick. Identify true cash flow, raise your extra payment by $55 each year, and compare line‑of‑credit rates before you deploy the strategy. By the end, listeners understand why $55 isn’t “nothing” (it’s $46,700 in saved interest and 2½ years of freedom) and why $500, when feasible, can erase $224,000 of interest and 12½ years of payments.Whether you’re a homeowner looking for a low‑effort shortcut or a seasoned investor seeking the most efficient debt‑paydown plan, CJ Wallace’s step‑by‑step calculations give you a clear roadmap to decide how much extra to throw at your mortgage—and when.
Categories: Money