This content is not available in your region
VC60-Your HELOC Is Maxed Out - Do NOT Do Velocity Banking. Do THIS - Velocity Channel
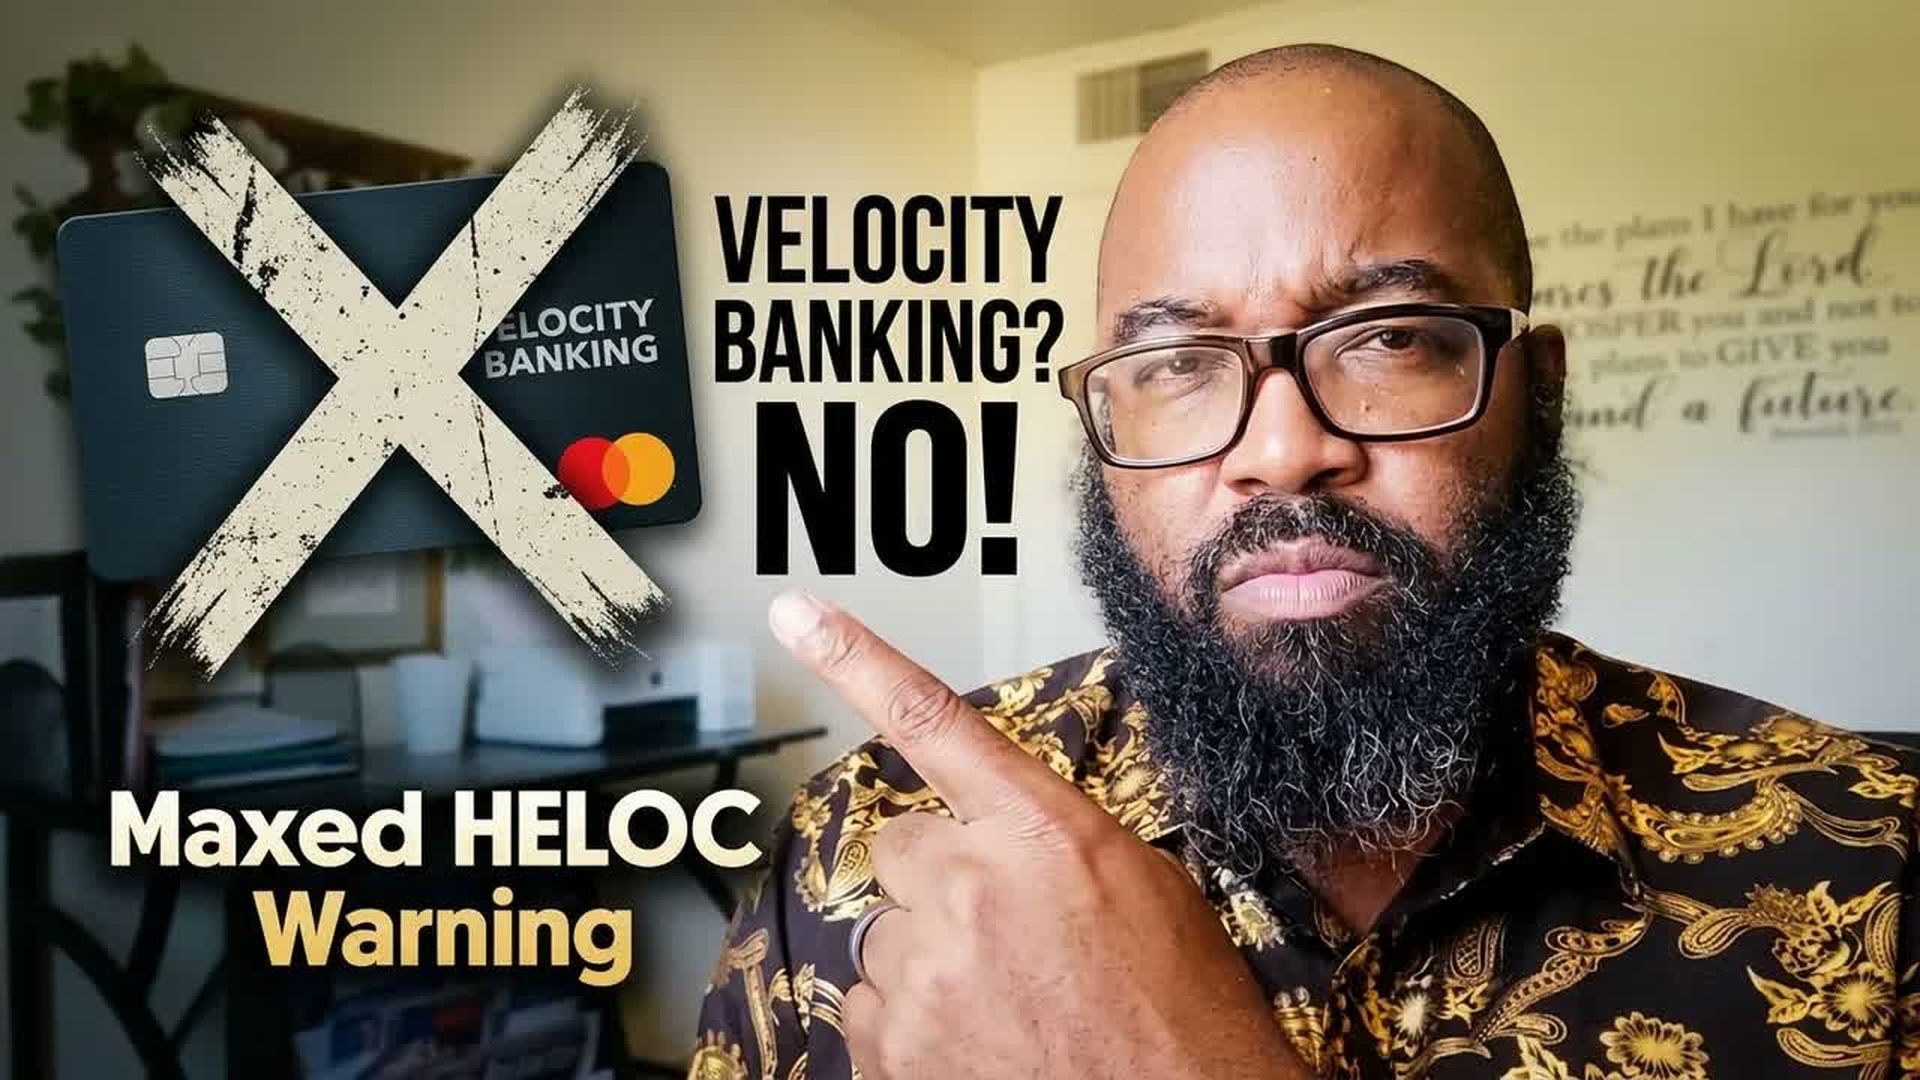
CJ Wallace fields a desperate listener’s question about using Velocity Banking when her HELOC is already maxed out. She earns $2,500 net each month, has a $500 spread, and faces brutal Texas property taxes plus adult‑daycare costs for a disabled spouse. Wallace explains why the strategy collapses without available credit: the “engine” needs room to pull a chunk, and a maxed line provides no fuel. He warns against opening a second line—that’s merely shuffling debt, not true Velocity Banking.The first priority, he says, is to restore the HELOC. At $25,000, 9.5 % variable, a $500 payment would clear it in 64 months, costing about $6,950 in interest. Next, he stresses budgeting on net income, not gross, because you can only service debt with take‑home pay. Plugging gross figures creates a phantom spread that inevitably fails.Wallace then pivots to a uniquely Texan remedy. In November 2025 voters approved Proposition 13 (raising the homestead exemption on school taxes to $140,000) and Proposition 11 (boosting the disabled/65+ exemption to $60,000). Stacked together they can shave $200,000 off a school‑taxable value, freezing the school‑tax ceiling at the qualifying amount—and it can even drop, never rise. He walks through the paperwork: filing Form 50‑126 to lock the ceiling, and Form 50‑114 with a disability verification to claim the exemptions. He notes the Comptroller’s 5 % annual penalty and the 181‑day deadline for deferred taxes.For the adult‑daycare expense, Wallace lists three alternative funding sources: Medicaid Home and Community‑Based Services, the Veterans Administration (if eligible), and possible tax deductions or the dependent‑care credit. He advises contacting the local Area Agency on Aging for assistance.Once the HELOC is cleared, Wallace outlines the next steps: funnel the $500 monthly spread back onto the mortgage principal ($182,400 at 6.75 %). That slashes the loan term from 30 years to roughly 14 years, saving $143,666 in interest. He demonstrates how higher rates actually accelerate the payoff, so waiting for lower rates is futile.The episode concludes with a clear “no” to the original Velocity Banking plan—at least for now—but promises that the tax‑exemption strategy could change the financial picture dramatically within five years.
Categories: Money